My Husband Canceled My Ultrasound Over $680—Then I Saw What He’d Done With Our Baby’s $20,000
I thought the app had loaded the wrong account.
I refreshed it.
Sixty-three dollars and eleven cents.
I closed the screen.
Opened it again.
Sixty-three dollars and eleven cents.
Diane leaned toward me.
“What is it?”
I turned the phone so she could see.
Her face changed.
Derek looked at the ceiling.
That was the moment I stopped asking whether there had been a mistake.
People who are surprised look at the number.
People who already know look somewhere else.
“Where is it?” I asked.
He exhaled.
“Claire, not here.”
“Where is the money?”
“We can talk at home.”
“No.”
The billing coordinator quietly stood.
“I can give you privacy.”
I looked at her.
“Thank you.”
She left and closed the door.
Diane stayed.
Derek noticed.
“Mom, can you give us a minute?”
“No.”
His jaw tightened.
“This is between me and my wife.”
Diane looked at him with an expression I had never seen before.
“She is thirty-six weeks pregnant, her insurance is inactive, and the money you told both of us was for her care is missing.”
Then she sat back.
“I’m staying.”
Derek rubbed his forehead.
“The money isn’t gone.”
I held up my phone.
“Then where is it?”
“It moved.”
“To where?”
“I made some investments.”
My ears started ringing.
“What investments?”
“Short-term.”
“What does that mean?”
He looked at Diane.
Then back at me.
“Sports positions.”
For a second, I genuinely did not understand.
Then I did.
“Betting.”
“It’s not the same thing.”
Diane made a sound under her breath.
I stared at my husband.
“You gambled our baby savings.”
“No.”
“Yes.”
“No. I used a portion of it temporarily.”
“There are sixty-three dollars in the account.”
He looked irritated now.
That was almost more frightening than guilt.
“You don’t understand how the platform works.”
“I understand subtraction.”
Diane closed her eyes.
I asked, “How much did you lose?”
“It isn’t a loss until—”
“How much?”
He did not answer.
I stood.
Too quickly.
The room tilted.
Diane caught my elbow.
“Sit down.”
“I’m fine.”
“You’re not.”
She was right.
I sat.
My daughter moved inside me.
One slow roll beneath my ribs.
I put my hand there.
Derek said, “I can fix it.”
That sentence.
I had heard it before.
After a late credit-card payment.
After he forgot to renew the car registration.
After a check bounced because he moved money without telling me.
Always temporary.
Always fixable.
Always somehow my reaction was the bigger problem.
I asked, “Is Atlantic City work?”
Silence.
My stomach turned.
“Derek.”
“It’s partly work.”
“What part?”
“There are people I need to meet.”
“At a casino?”
He looked at Diane.
“She doesn’t know what she’s talking about.”
I laughed once.
“I know enough.”
He pulled out his phone.
“My flight leaves in an hour.”
“Then miss it.”
His face snapped toward me.
“I’ve already paid for the hotel.”
“With what?”
Silence again.
I knew.
“The baby account?”
“No.”
“Your mother’s eight thousand?”
“No.”
“Then show me.”
He stared at me.
I held out my hand.
“Show me the charge.”
He did not.
Diane said, “Derek.”
“Mom, stop.”
“No. You asked me for eight thousand dollars because you said Claire was worried about the hospital bill.”
“I was going to replace it.”
“You asked me for another five this morning.”
Everything inside me went still.
I looked at Diane.
“What?”
She opened her bag.
Not dramatically.
Just carefully.
She removed her phone.
At 6:12 that morning, Derek had texted her.
Insurance mess is worse than we thought. Hospital wants another $5,000 before delivery. I hate asking. Claire’s already stressed. If you can help, I’ll pay you back by Christmas.
I read it twice.
Then looked at him.
“You asked her for five thousand dollars today.”
“It was contingency.”
“For the hospital?”
“I was going to use it to cover things.”
“What things?”
He said nothing.
Diane said, “That’s why I came here.”
I looked at her.
“I was going to transfer it,” she continued. “Then I thought if the clinic needed that much, I should pay them directly.”
Derek swore.
Not loudly.
Enough.
Diane’s face hardened.
“I came because I was trying not to accuse my son of lying before I had proof.”
I looked at the ultrasound photograph still in her lap.
She had proof now.
So did I.
I called the bank back.
Derek reached for my phone.
I moved it away.
“What are you doing?”
“Reviewing transactions.”
“Claire.”
I held up one finger.
The representative confirmed that as a joint owner I could request recent account activity.
I asked for the last ninety days.
The answer came line by line.
Three transfers to Derek’s personal checking.
Two payments to a major online sportsbook.
A credit-card payment.
Then another transfer labeled only with a payment processor I did not recognize.
I asked for the amounts.
Four thousand.
Six thousand five hundred.
Three thousand.
Two thousand four hundred.
More.
The numbers blurred.
Diane wrote them down.
When the representative finished, the total outflow from the baby savings account over seven weeks was $19,936.89.
The account had started with twenty thousand dollars.
Sixty-three eleven remained.
I asked about the eight thousand Diane sent to Derek’s personal account.
The bank representative could not discuss an account I did not own.
That mattered.
Even married people do not automatically have rights to each other’s individually titled bank information.
I knew that.
What I had rights to was the truth about our joint money.
And I finally had enough of it.
I ended the call.
Derek said, “Now can we go home?”
“No.”
His expression changed.
“What do you mean?”
“I’m not going home with you.”
He laughed as if I were performing.
“You’re thirty-six weeks pregnant.”
“I know.”
“You’re being ridiculous.”
Diane stood.
“No.”
He looked at her.
She pointed toward the door.
“You are.”
That was the first time I ever saw my mother-in-law choose my side against her son.
It did not feel victorious.
It felt terrible.
Families should not need sides in a medical office.
But sometimes clarity arrives after neutrality becomes impossible.
Derek looked at me.
“Where are you going?”
“With Diane.”
His face went blank.
“Seriously?”
“Yes.”
“She lives forty minutes away.”
“I know.”
“You have work Monday.”
“I know.”
“The nursery is at home.”
“I know.”
He stepped closer.
“Claire, this is insane.”
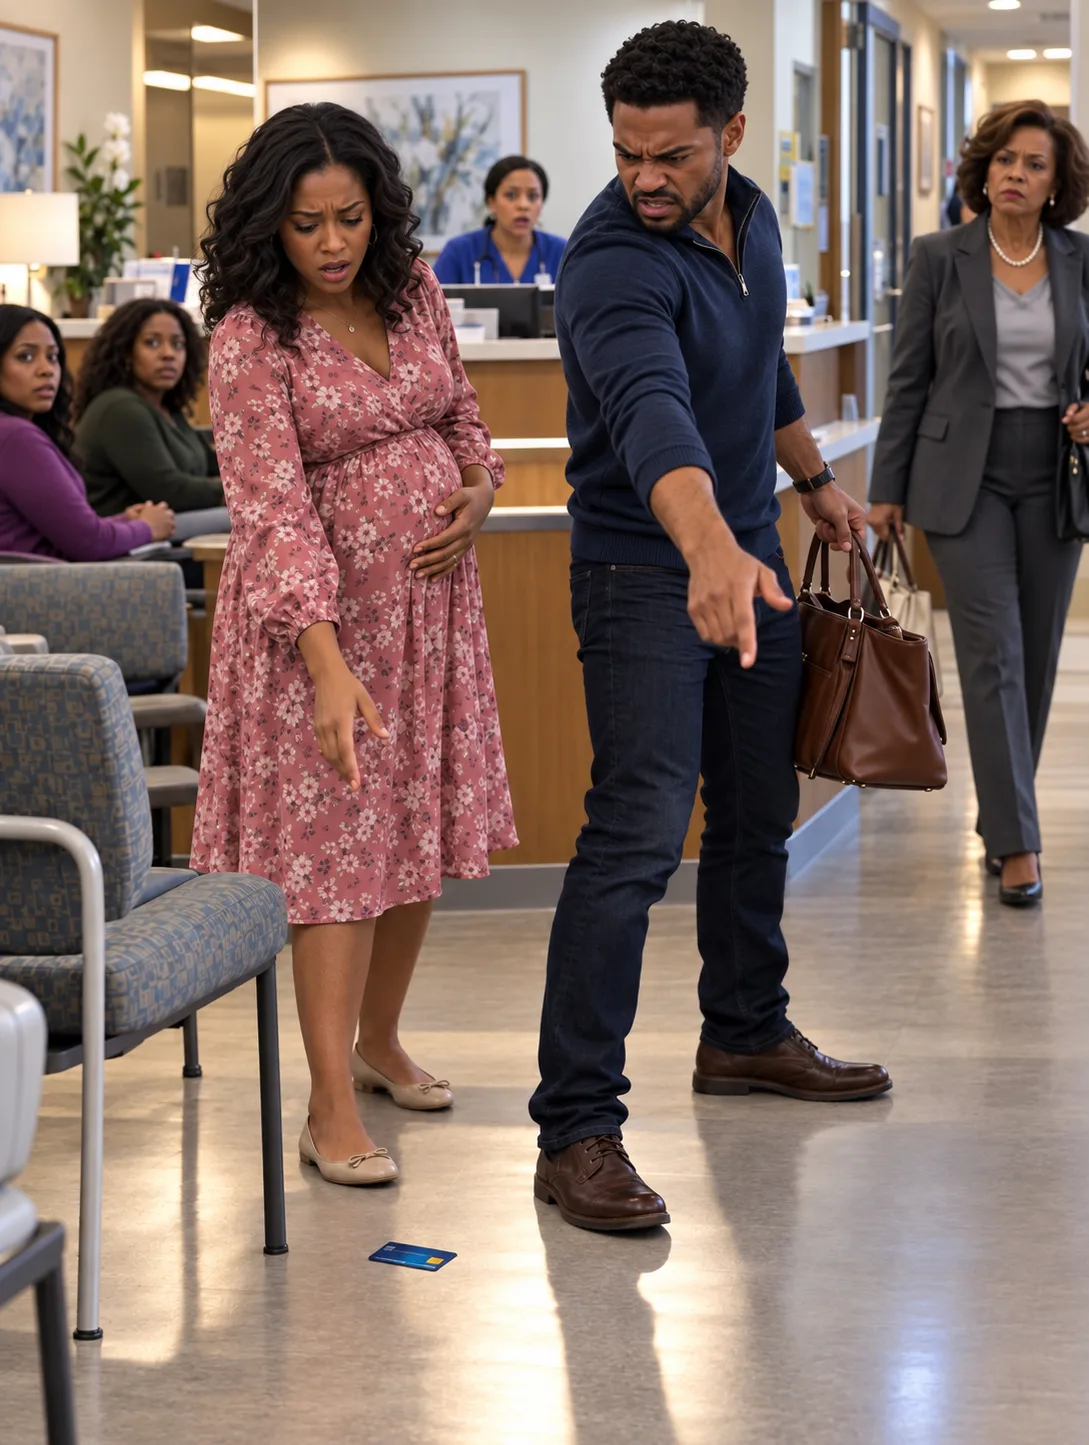
I looked at the purse he had taken from me twenty minutes earlier.
The card he knocked from my hand.
The canceled insurance he called a billing mistake.
The empty savings account.
Then I said, “No. This is what happens when I finally believe the numbers.”
He left for the airport.
That shocked me more than anything.
He actually went.
While Diane drove me to her house, his location appeared briefly through the family sharing app at the airport parking garage.
Then the sharing stopped.
He turned it off.
Diane saw my face.
“What?”
“He went.”
She gripped the steering wheel.
“I’m sorry.”
I looked out the window.
“For what?”
“For raising a man who thinks leaving is the same as solving.”
I did not know what to say to that.
So I said nothing.
At her house, I called my obstetrician’s office again.
The billing coordinator had already asked someone to investigate the insurance status.
By three that afternoon, I had an answer.
The policy had not lapsed because of a billing mistake.
Derek had changed jobs three months earlier.
I knew about the new job.
What I did not know was that he had chosen employee-only coverage at the new company.
He told me the family plan transfer was “still processing.”
It had never been elected.
My coverage under his prior employer had ended.
I had been uninsured for nearly nine weeks.
I sat at Diane’s kitchen table holding the phone.
“Why would he do that?”
The benefits representative could not answer motive.
She could only tell me what their records showed.
During enrollment, Derek had selected coverage for himself.
No spouse.
No dependent.
I asked whether I could enroll now.
She explained that eligibility would depend on the plan rules and whether a qualifying event or correction applied.
She gave me a number for the benefits administrator.
My obstetrician’s office also connected me with a patient financial counselor who helped me review options for maternity coverage, payment arrangements, and an expedited application through the appropriate channels.
Nothing was magically fixed that afternoon.
But something important happened.
For the first time, people gave me accurate information.
Not reassurance.
Information.
There is a difference.
By dinner, I knew what I owed so far.
What claims were pending.
What insurance gap existed.
What paperwork I needed.
I also knew Derek had lied about every part of it.
Diane made soup.
I barely ate.
At nine, he texted.
Landed. Can we not blow up our marriage before I get back?
I stared at the message.
Then another came.
I can replace the money.
Then:
You are making this worse by involving my mother.
I did not answer.
At ten fourteen, another.
Baby okay?
That one I answered.
She is okay.
Nothing else.
The next morning, Diane drove me to the bank.
I opened a new checking account in my name only and changed the direct deposit from my extra enrollment shifts to that account.
I did not empty the joint household account.
I did not move his paycheck.
I did not try to punish him financially.
I simply stopped placing new earnings where I no longer trusted access.
Then I requested complete statements for every joint account I legally had access to.
I also pulled my credit reports.
That was when I found the credit card.
Opened seven months earlier.
Joint.
Balance: $14,870.
I had never seen it.
My name was listed as co-borrower.
I stared at the screen.
Diane said, “Did you sign for that?”
“I don’t know.”
I hated the answer.
Too much of my marriage had lived inside I don’t know.
I called the issuer.
The account had been opened online.
I requested the application records.
Then I called a family-law attorney.
Her name was Laura Chen.
She asked one question before anything else.
“Are you physically safe?”
“Yes.”
“Are you sure?”
I thought of Derek knocking my debit card from my hand.
Taking my purse.
Not hitting me.
Not threatening me.
Still.
The question changed how I framed the scene.
“He controls money.”
“How?”
I told her.
The savings.
The insurance.
The card.
The hidden credit account.
Atlantic City.
The eight thousand from Diane.
Laura did not tell me to divorce him.
Good lawyers rarely begin by telling clients what life decision to make.
She told me what to preserve.
Bank statements.
Texts.
Benefits records.
The clinic receipt.
Diane’s transfer receipt.
Credit reports.
She also told me not to sign anything Derek put in front of me without review.
That advice arrived about eight years too late.
Still useful.
“What do I do about the baby?”
“You keep receiving medical care.”
“I mean when she’s born.”
Laura paused.
“Have you decided whether you want Derek present at the hospital?”
“No.”
“Then you do not need to decide today.”
That nearly made me cry.
Pregnancy had become a countdown where everyone wanted decisions.
Birth plan.
Visitors.
Names.
Feeding.
Leave.
Insurance.
Marriage.
For once, someone gave me permission not to decide everything immediately.
Derek returned Sunday night.
He came to Diane’s house with flowers.
Not for me.
For his mother.
That told me something.
He rang the bell.
Diane opened the door but did not step aside.
“Can I come in?”
“No.”
“Mom.”
“Claire asked for space.”
“She is my wife.”
“Yes.”
“She’s carrying my daughter.”
“Yes.”
“Then move.”
Diane’s face changed.
“Do not speak to me like that.”
He looked past her.
“Claire!”
I came into the hallway.
Diane asked, “Do you want him inside?”
That question again.
Do you want him?
Choice.
My answer came easier this time.
“For ten minutes.”
She let him in.
We sat in the living room.
He looked tired.
Not ashamed.
Tired.
“I fixed it,” he said.
I almost laughed.
“What?”
“The betting account.”
“How?”
“I won enough this weekend to cover most of the baby fund.”
Diane closed her eyes.
I stared.
“You gambled more.”
“I won.”
“With what money?”
He stopped.
“Derek.”
“Credit.”
My skin went cold.
“How much?”
“It doesn’t matter. I won.”
“That matters more.”
He leaned forward.
“Claire, listen to me. I have twenty-two thousand sitting in the account now.”
“Which account?”
“My personal checking.”
“Show me.”
He did.
For once, the number existed.
$22,184.
I felt nothing.
No relief.
Because I had finally understood the problem was not whether one gamble happened to win.
The problem was that our family security depended on whether he could keep making the next bad decision work.
I said, “Transfer twenty thousand back to the joint baby savings account.”
His expression changed.
“Why?”
“Because it was taken from there.”
“I’m going to use some to pay the card.”
“The hidden card?”
He froze.
“How did you find that?”
“Credit report.”
He looked angry.
“You’re checking up on me now?”
I could not believe the question.
“Yes.”
The honesty startled him.
“Yes, Derek. I am checking.”
He stood.
“This is exactly why I don’t tell you everything.”
I looked at him.
“Because I might know it?”
He swore.
Diane said his name sharply.
I continued.
“Transfer the twenty thousand.”
“No.”
There it was.
The money existed.
He still believed control belonged to him.
I did not argue.
I looked at Laura’s business card on the table.
Derek followed my eyes.
“You hired a lawyer?”
“I consulted one.”
He went pale.
“Claire.”
“You canceled my insurance.”
“I was going to add you after the baby.”
“That sentence doesn’t even make sense.”
“The premium was insane.”
“So you chose not to insure your pregnant wife.”
“I thought the old plan ran through the month.”
“For nine weeks?”
He rubbed his face.
“It got away from me.”
“The savings?”
“I was trying to multiply it.”
“The eight thousand?”
“I was going to use it for the hospital after I made the money back.”
“The five thousand you asked your mother for?”
He said nothing.
“The credit card?”
“Expenses.”
“Atlantic City?”
He looked away.
I said, “You are not having a money problem.”
His jaw tightened.
“You are having a lying problem.”
That ended the conversation.
He left.
The next week, he transferred twelve thousand dollars back.
Not twenty.
Twelve.
He used the rest to pay down the hidden credit card and what he called “outstanding positions.”
Laura said not to fight over the number by text.
Document.
Preserve.
Do not negotiate emotionally.
So I did.
I worked until thirty-eight weeks.
Not because I was heroic.
Because paid leave mattered.
Because my direct deposit now entered an account I controlled.
Because every shift made me feel less trapped.
The benefits issue partially resolved through a special enrollment review tied to the job transition and employer communications, though some claims remained my responsibility.
I set up payment plans.
Diane insisted on covering the ultrasound she had already offered to pay for.
I accepted.
Not because I wanted to owe her.
Because she said something that changed my mind.
“This is not a loan. It is not leverage. It is a gift to my granddaughter.”
Clear terms.
I had learned to value them.
At thirty-nine weeks and two days, my water broke at Diane’s kitchen table.
She stared at the floor.
Then at me.
“Is that—”
“Yes.”
“Oh.”
For a woman who had confronted her son in a clinic, she became remarkably useless.
I laughed.
That helped.
She drove me to the hospital.
Derek knew labor had begun because I texted him myself.
I had decided days earlier he could be there if he respected my boundaries.
He arrived forty minutes later.
No casino confidence.
No arguments.
Just pale.
The nurse asked me privately whether I wanted him in the room.
“Yes.”
That yes felt different because I knew I could have said no.
Our daughter, Emma, was born seven hours later.
Seven pounds, nine ounces.
Healthy.
Loud.
Perfect in the way newborns are perfect even while looking mildly offended by existence.
Derek cried when he held her.
So did I.
For one dangerous hour, the hospital room felt like the life I had expected.
A husband.
A wife.
A baby.
Grandmother.
Photographs.
Then reality returned.
Emma’s birth did not erase bank statements.
It did not reactivate insurance.
It did not replace trust.
When Derek said, “We can fix everything now,” I looked at our daughter.
“No.”
His face fell.
“We can see whether you fix yourself.”
That was different.
I went home to Diane’s house with Emma.
Derek went to ours.
For six weeks, we lived separately.
He started attending a gambling treatment program.
At first, I was suspicious.
Then I learned I did not have to decide whether his recovery was sincere immediately.
Time could answer.
He gave Laura’s office complete financial disclosures voluntarily.
Not because he had become noble.
Because my attorney made clear that if separation became divorce, disclosure would happen anyway.
The picture was worse than I knew.
Over eighteen months, Derek had lost roughly $31,000 through sports betting and casino play.
Some wins had temporarily hidden losses.
He had used bonuses.
Savings.
Credit.
The money from Diane.
Then more credit.
Atlantic City had produced a win large enough to replace part of the baby fund, which was why he came back convinced he had solved the problem.
He had not.
He had simply received the perfect reward for continuing the behavior.
The hidden joint credit card became another issue.
The application records showed my information had been entered online.
The electronic authorization used my email address.
But the verification email had been routed automatically into a folder Derek managed through our shared account.
I did not remember agreeing.
He insisted I had clicked something months earlier when we refinanced an appliance purchase.
Laura advised me not to make accusations we could not prove.
So I did not call it forgery.
I called it what I knew.
A debt opened in both our names that he did not disclose to me.
That was enough.
Three months after Emma’s birth, Derek asked to move back in.
I said no.
He looked devastated.
“I haven’t gambled in ninety-two days.”
“I know.”
“I go to meetings.”
“I know.”
“I gave you access to everything.”
“Yes.”
“What else do I have to do?”
“Keep doing it.”
“For how long?”
I looked at him.
“That question is why you’re not ready.”
He sat back.
I continued.
“You keep treating trust like an invoice. Three meetings, one apology, ninety-two days, now I owe you the marriage back.”
He went quiet.
I said, “Trust is not a bill I pay because you completed the program.”
That was the first conversation where I thought he truly understood.
Not because he said the right thing.
Because he stopped arguing.
He rented a small apartment.
Paid child support under an interim agreement.
Continued treatment.
Closed every betting account he could close and used blocking tools recommended through his program.
Diane did not manage his recovery.
That was important.
She had spent years rescuing him quietly.
A late credit-card payment.
A rent shortage in college.
A business idea that needed five thousand dollars.
She realized she had helped teach him that consequences arrived with family money behind them.
She stopped.
When he asked her for a loan to consolidate debt, she said no.
Then cried for two days.
Boundaries hurt the people setting them too.
Six months after Emma’s birth, Derek and I entered couples counseling.
Not reconciliation counseling.
Assessment.
I needed to know whether the marriage had anything left besides history and a child.
In one session, the counselor asked him why he knocked the debit card from my hand.
He said, “I panicked.”
“About what?”
“That she would pay.”
I stared at him.
The counselor waited.
He continued.
“If she paid the six eighty herself, the clinic would keep asking why insurance wasn’t active.”
“And?”
“She would find out.”
There it was.
The card had never been about $680.
It was about delay.
He was trying to stop information from moving.
That realization changed the memory completely.
He had made me feel irresponsible for spending money.
In reality, I was seconds away from learning the truth he had spent months hiding.
The counselor asked, “Why take her purse?”
Derek looked ashamed.
“To end the appointment.”
“By controlling whether she could pay.”
“Yes.”
I felt sick.
Not because the fact was new.
Because he said it plainly.
Financial control.
It did not require him to forbid me from working.
I did work.
It did not require him to give me an allowance.
He did not.
Control had looked like passwords changed without telling me.
Accounts moved.
Insurance decisions made alone.
Information withheld until I could not make an informed choice.
Then calling me dramatic when I noticed.
Naming it did not automatically end our marriage.
But it ended my confusion.
A year after Emma was born, we were still living apart.
People found that strange.
“Either forgive him or divorce him.”
Families love binary advice.
Real life is slower.
Derek had not gambled for over a year.
He had repaid the remainder of the baby savings.
The hidden credit card was closed and paid under a plan that required him to cover the majority from his discretionary income.
He contributed reliably to Emma’s expenses.
He showed up.
He learned her pediatrician’s name.
Her feeding schedule.
Her daycare closure dates.
He stopped treating fatherhood like a role I managed and he visited.
I noticed.
Then one afternoon, I noticed something else.
I was no longer checking the joint-account app every hour.
Not every day either.
Maybe twice a week.
Trust does not return as a feeling first.
Sometimes it returns as the absence of monitoring.
That frightened me.
It also gave me hope.
We eventually reconciled.
Eighteen months after Emma’s birth.
Not because the story needed us to.
Because by then, the evidence had changed.
He moved back under written financial rules we both agreed to.
Separate personal accounts.
One joint household account.
One joint emergency account requiring notification for transfers above a set amount.
Both of us had access to insurance portals.
Both of us knew passwords.
No new debt without disclosure.
Monthly financial check-ins.
Not romantic.
Excellent.
Our marriage became less romantic in the fantasy sense and more intimate in the factual one.
There were fewer surprises.
That was the point.
Diane never gave Derek money privately again.
If she wanted to gift something for Emma, she told both of us.
The first Christmas after we reconciled, she gave us a check for five hundred dollars.
On the memo line she wrote:
Emma—books, clothes, or savings. Parents decide together.
I laughed.
Derek did too.
Then he looked at me.
“Too specific?”
“No.”
“Not anymore.”
Three years later, I still have the ultrasound photograph from that day.
It is in Emma’s baby book.
On the opposite page is the receipt Diane brought to the clinic.
Not because I want my daughter to grow up reading about her father’s worst year.
She will learn age-appropriate truth when she is older.
I kept the receipt because it marks the day I stopped treating money as a private language only Derek spoke.
For most of our marriage, he handled insurance.
Investments.
Accounts.
Passwords.
I handled groceries, childcare, appointments, and the thousand daily expenses that kept a home alive.
We called that division of labor.
It became dangerous when division turned into secrecy.
Now I know what our insurance costs.
He knows what daycare costs.
I know what is in retirement.
He knows how much I spend on groceries.
Neither of us asks permission for normal personal purchases.
Both of us disclose debt.
That is not surveillance.
It is partnership.
I also kept working after Emma was born.
The extra enrollment shifts became a permanent position in student services when she was eighteen months old.
The pay was modest.
Steady.
Mine.
Not because I needed an escape fund.
Though having independent income matters to me now.
Because I like my work.
Derek once asked whether my job made me feel safer than he did.
I answered honestly.
“Sometimes.”
That hurt him.
He said, “Fair.”
Growth can be embarrassingly uncinematic.
One word.
Fair.
Years earlier, he would have turned my fear into an accusation.
Now he could let it exist.
There was one more part of rebuilding that neither of us expected to be difficult.
Taxes.
The first year after Emma was born, we sat at the kitchen table with our accountant and I realized how many financial decisions I had once allowed Derek to summarize for me.
Retirement contributions.
Flexible spending.
Insurance elections.
Interest.
Debt balances.
I kept interrupting.
“What does that line mean?”
“What happens if we choose this?”
“Why is that account separate?”
At first, Derek answered too quickly.
Then he caught himself.
He slowed down.
The accountant did too.
Nobody rolled their eyes.
Nobody said, “I’ve got it.”
I wrote notes.
Asked the same question twice when I needed to.
Afterward, Derek said, “I used to think explaining all of this would stress you out.”
I looked at him.
“No. You thought not explaining it would make things easier.”
He winced.
“Yes.”
“For you.”
“Yes.”
That was the difference.
Information can be inconvenient inside a relationship.
It can slow decisions.
Create disagreement.
Expose mistakes.
But convenience is not the same as safety.
The next month, I added one more rule to our written financial plan.
If one of us does not understand a financial decision, the decision waits.
Derek agreed.
That sentence has saved us from more arguments than any budgeting app ever did.
It also changed the way I thought about Emma’s future.
When she is old enough, I want her to know what insurance is before she needs it.
What a credit report is.
What joint debt means.
Why passwords matter.
How to read a bank statement.
Not because I expect her to distrust the person she someday loves.
Because trust should be informed.
I had once believed asking questions meant I lacked faith in my husband.
Now I understand that questions are how adults participate in their own lives.
Emma is four.
She has no memory of the clinic.
No memory of Diane holding my debit card.
No memory of a savings account with sixty-three dollars and eleven cents.
Good.
Children should not inherit every crisis their parents survive.
But I hope she inherits what came after.
The habit of asking questions.
The confidence to keep access to her own money.
The knowledge that love does not require ignorance.
And the certainty that medical care is not a luxury someone else gets to cancel because the truth behind the bill is inconvenient.
Sometimes I think about the exact moment everything changed.
People assume it was seeing the account balance.
It was not.
The balance was proof.
The real change came five minutes earlier.
Nurse Megan stood at the hallway entrance and asked:
“Claire, would you like your husband to come in?”
A simple question.
I was thirty-six weeks pregnant.
Married.
Financially entangled.
Scared.
And for the first time that morning, someone treated my preference like the deciding fact.
“No,” I said.
“I’d like Diane.”
That no led me to the ultrasound.
The receipt.
The billing office.
The bank call.
The sixty-three dollars.
The lawyer.
The truth.
Derek knocked my card out of my hand because he needed me not to pay.
He needed me not to ask.
He needed the appointment to end before information arrived.
Instead, the appointment continued without him.
That is the part I remember.
Not that his mother rescued me.
She helped.
Not that the bank saved me.
It gave me numbers.
Not that a lawyer told me what to do.
She gave me options.
I saved myself the way adults usually do.
Not with one dramatic act.
By staying on the call.
By asking for the statement.
By opening another account.
By reading the benefits record.
By saying no when someone expected yes.
By waiting until behavior—not promises—became evidence.
And every year, on Emma’s birthday, I move a little money into her savings account.
Not twenty thousand dollars.
Whatever we can afford.
Fifty.
One hundred.
Sometimes more.
Both our names are on the account as custodians for her.
Both of us can see it.
No secrets.
Last month, the balance crossed twenty thousand again.
I noticed while drinking coffee.
For a moment, I stared at the number.
Then I called Derek into the kitchen.
He looked over my shoulder.
Neither of us spoke.
Finally he said, “That took a while.”
“Yes.”
“I’m sorry.”
“I know.”
He touched my back.
I let him.
Then the screen dimmed.
This time, I did not need to refresh it.
The money was there.
So was the trust.
May you like
Not because either one had magically returned.
Because, slowly, deliberately, we rebuilt both.